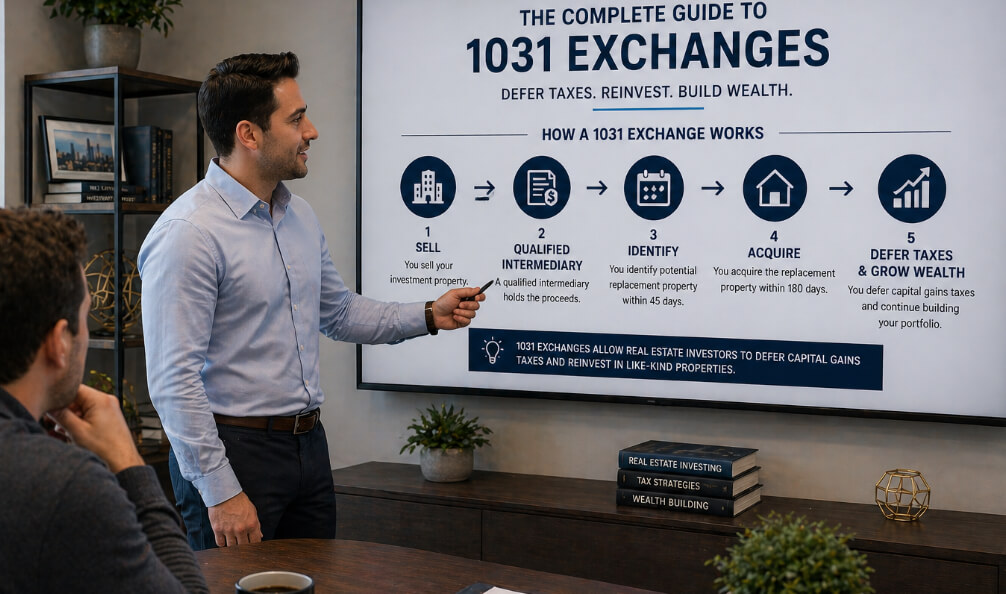
A 1031 exchange lets a real estate investor sell an investment property and reinvest the proceeds into another without paying capital gains tax at the time of sale. The tax is deferred, not erased — but deferral compounds, and investors who chain exchanges across decades keep capital working that would otherwise have gone to the IRS.
It is also unforgiving. Miss a deadline by a day, touch the money for an hour, or misidentify a property, and the entire exchange collapses into a fully taxable sale.
What qualifies
Only investment or business real property. Since the 2017 tax law, personal property no longer qualifies — the provision is real-estate only. Your primary residence does not qualify. Neither does property held primarily for resale, which is why flippers generally cannot use it.
“Like-kind” is broad for real estate. An apartment building can be exchanged for raw land, a retail strip for a single-family rental, a warehouse for farmland. The properties must both be held for investment or productive use in a trade or business — the type of real estate does not have to match.
Both properties must be in the United States. Foreign real estate is like-kind only to other foreign real estate.
The two deadlines that govern everything
From the day your relinquished property closes:
- 45 days to identify replacement property in writing to your qualified intermediary.
- 180 days to close on the replacement property.
These run concurrently, not consecutively — the 180 days includes the 45. And the 180-day period is further capped by your tax return due date for that year, including extensions. Sell in November without filing an extension and your window shortens sharply.
There are no extensions for weekends, holidays, financing delays, or a deal falling through. The only relief comes from IRS disaster declarations. This is why experienced exchangers line up replacement candidates before listing the relinquished property, not after.
The identification rules
Your written identification must follow one of three rules:
- Three-property rule — identify up to three properties of any value. This is what most exchangers use.
- 200% rule — identify any number of properties, provided their combined fair market value doesn’t exceed 200% of what you sold.
- 95% rule — identify any number of any value, but you must actually acquire at least 95% of the total identified value. Rarely used, and risky.
Identification must be unambiguous — a full street address or legal description, signed and delivered to the intermediary by day 45. “A duplex in Phoenix” is not identification.
The qualified intermediary is mandatory
You cannot touch the sale proceeds. If the funds pass through your hands or your control at any point, the IRS treats the transaction as a sale and the exchange is dead.
A qualified intermediary (QI) holds the proceeds between closings and handles the exchange documentation. The QI cannot be your attorney, CPA, real estate agent or employee if they have served you in that capacity within the past two years — those are disqualified persons.
QIs are lightly regulated. Vet them: ask about fidelity bonding, errors and omissions coverage, whether funds are held in segregated qualified escrow accounts, and how long they have operated. Investors have lost entire exchange proceeds to QI failures.
Engage the QI before the relinquished property closes. After closing is too late — this is the single most common way exchanges are lost.
Avoiding “boot”
To defer the full gain, you generally need to:
- Buy equal or greater in value than what you sold, and
- Reinvest all the net proceeds, and
- Carry equal or greater debt (or offset a reduction with additional cash).
Anything you receive that isn’t like-kind property is boot, and boot is taxable. Cash boot is straightforward — you took money out. Mortgage boot is subtler: if you sell a property with a $400,000 mortgage and buy one with a $300,000 mortgage, that $100,000 debt reduction is treated as boot unless you add $100,000 of your own cash.
Partial exchanges are legal. You simply pay tax on the boot rather than losing the whole deferral.
Variations worth knowing
- Reverse exchange — you acquire the replacement first and sell afterwards, using an exchange accommodation titleholder. More complex and more expensive, but valuable in tight markets where you cannot risk selling before securing a replacement.
- Improvement (build-to-suit) exchange — exchange proceeds fund improvements on the replacement property, with the work completed within the 180 days.
- Delaware Statutory Trust (DST) — fractional interests in institutional property that qualify as like-kind. Popular with investors who want out of active management but not out of deferral. Illiquid, with fees and sponsor risk that deserve scrutiny.
The exit: recapture and the step-up
Deferred tax comes due when you eventually sell without exchanging — including depreciation recapture, taxed at up to 25% on the depreciation you claimed along the way, plus capital gains on appreciation, plus potentially the net investment income tax.
The long-standing planning route is to keep exchanging until death, at which point heirs may receive a stepped-up basis, potentially eliminating the deferred gain. This is a genuine feature of current law, and also a policy that has been repeatedly proposed for change. Plan on the law as it is, but do not build a family financial plan on the assumption it will never change.
Frequently asked questions
Can I 1031 into a property I’ll eventually live in? Converting a replacement property to a primary residence is possible but heavily regulated, with a minimum holding period as investment property and reduced capital gains exclusion on eventual sale. Get specific professional guidance.
Can I exchange a vacation home? Only if it meets strict rental-use and limited-personal-use tests. A personal vacation home does not qualify.
What does an exchange cost? QI fees commonly run $800–$1,500 for a standard forward exchange, more for reverse or improvement exchanges, plus your normal closing costs.
Can I do a partial exchange? Yes. You defer tax on the reinvested portion and pay on the boot.
What if I can’t find a replacement in 45 days? The exchange fails and the sale becomes taxable. This is why identification candidates should be lined up before you close the sale.
Before you list
Engage a qualified intermediary and speak with a CPA before the relinquished property goes under contract. Nearly every failed 1031 exchange traces back to a step taken too late rather than a rule misunderstood.

Be First to Comment